
How Does Property Finance Work for First-Time Commercial Buyers
Master real estate growth with strategic Property Finance solutions. Discover expert capital structures to fund commercial and residential assets.
Navigating the world of commercial real estate can feel like stepping into a whole new territory if you are used to residential home loans. The way you fund a business space is completely different, which is why understanding Property Finance early on makes all the difference in turning a business dream into a physical reality. When you step into this market, you are not just buying a building; you are securing an asset that needs to support your business goals or generate steady rental income. Getting a handle on Property Finance from the very beginning helps you clear out the confusion and build a clear path toward getting those keys.
Understanding the Basics of Focus Key Phrase and Commercial Mortgages
When you start looking at commercial properties, the first major adjustment is how lenders view your risk. Unlike standard home loans where lenders mostly focus on your personal salary and paycheck history, commercial lenders care far more about the property’s ability to pay for itself or your business’s overall financial health.
They will scrutinize your revenue, existing business debts, and cash flow projections. They want to make sure that whether the economy drops or stays steady, your business can comfortably make the monthly repayments without putting the entire operation under stress.
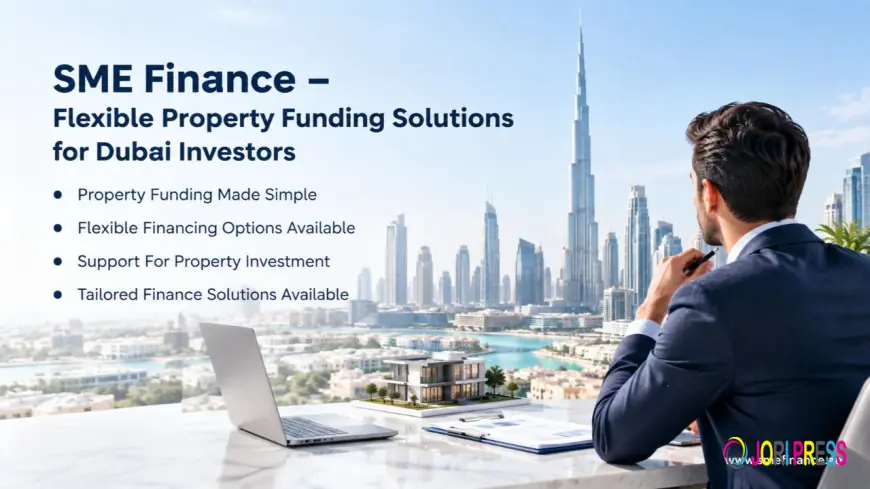
Note: SME Finance Banking Consultant specializes in comprehensive Property Finance Dubai offerings that align corporate borrowing needs with high-value real estate opportunities. Efficient debt structuring reduces financial risk while accelerating property development and acquisition workflows. Schedule a consultation with our experts today to elevate your real estate financial strategy.
Key Features of Focus: Key Phrase for Beginners
Before you sign any paperwork or approach a bank, it is worth looking closely at how these loans are built. Commercial funding comes with unique rules and features that shape your long-term commitment:
-
Shorter Loan Terms: While a house mortgage might stretch over 30 years, commercial property loans usually span between 5 and 15 years, often paired with balloon payments or refinancing options at the end.
-
Higher Down Payments: Lenders typically expect you to put down anywhere from 20% to 40% of the total purchase price upfront, as they consider commercial ventures higher risk.
-
Variable Interest Rates: Rates are often tied to broader economic benchmarks, meaning your monthly payments might fluctuate over the life of the loan depending on market conditions.
-
Property Evaluation Rigor: The lender will hire professional appraisers to evaluate the building's income potential, location quality, and structural health before approving a single dollar.
To make sure your transaction runs smoothly, having access to commercial mortgage solutions tailored to your specific industry will give you leverage when negotiating loan structures with traditional banks or private lenders.
The Step-by-Step Approval Process for Commercial Property Finance
Getting approved is a journey that requires patience, organization, and a solid stack of documentation. Lenders do not just look at your credit score; they want to see your entire business model laid out clearly. You will need to present up-to-date profit and loss statements, balance sheets, tax returns for the past few years, and a realistic business plan showing how the property directly benefits your bottom line.
Once you submit your application, the lender enters the underwriting phase. During this time, they assess the commercial risk, review local market trends, analyze potential lease agreements if you plan to rent out space, and perform legal checks. If everything aligns and your income covers the required debt coverage ratio, the lender will extend a formal offer setting out your interest rates, fees, and repayment schedules.
Smart Strategies to Secure the Best Funding Terms
Getting approved is one thing, but getting terms that do not strangle your daily operational cash flow is another. To put yourself in the strongest position possible, start by cleaning up existing business debts and building up strong cash reserves well before you apply. Lenders love seeing that you have extra buffer cash available in case your business faces a slow quarter or unexpected building maintenance costs arise.
Additionally, consider working with specialists who understand how different lenders evaluate business income. Different banks have vastly different appetites for specific industries—some prefer light industrial spaces, while others favor retail or office complexes. Matching your property type with the right financial provider can save you thousands of dollars in interest and fees over the term of your loan.
Conclusion
Taking your first step into commercial real estate is a major milestone that can elevate your business to an entirely new level of stability and growth. While the borrowing process involves tighter scrutiny, higher deposit requirements, and different risk evaluations than a traditional mortgage, it becomes straightforward once you break down how the pieces fit together. By preparing your business financials carefully and understanding your long-term funding needs, you can secure a space that powers your ambition for years to come. For expert guidance throughout your journey, partnering with an experienced SME Finance Banking Consultant ensures you find the right borrowing path and negotiate terms designed to keep your business growing.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0