
Micro Data Center Market Size, Share & Growth Forecast 2033
Micro Data Center Market to reach USD 33.0 billion by 2033, growing at 20.0% CAGR, driven by edge computing, 5G, IoT, and AI.
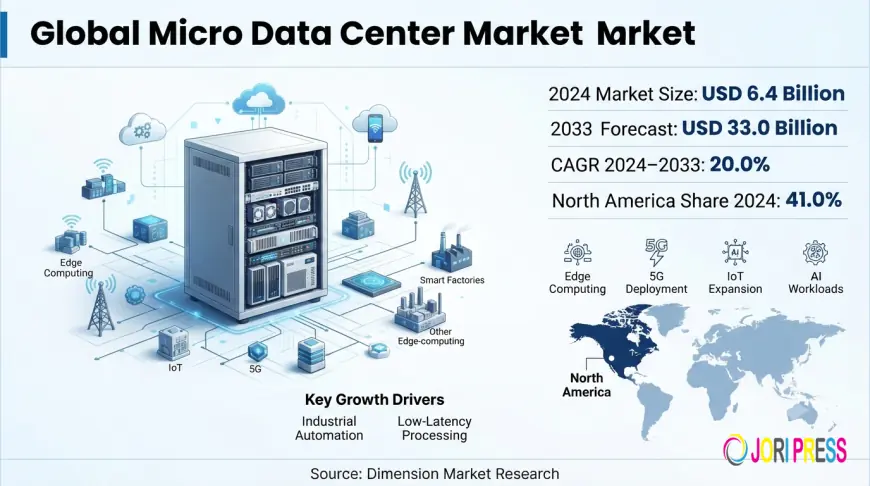
The Global Micro Data Center Market Size is expected to reach USD 6.4 billion in 2024 and is projected to attain USD 33.0 billion by 2033, expanding at a strong CAGR of 20.0% during the forecast period. Micro data centers are emerging as an important part of modern digital infrastructure because enterprises increasingly require localized computing capacity, low-latency processing, secure data handling, and reliable IT environments closer to users, devices, and operational facilities.
Growing adoption of edge computing, artificial intelligence, Internet of Things applications, 5G networks, industrial automation, and cloud-connected infrastructure is reshaping data-processing requirements across industries. Traditional centralized facilities remain essential, but organizations are increasingly complementing them with compact, modular data centers positioned closer to the point where information is generated. This architecture enables enterprises to process time-sensitive data faster while improving operational continuity and reducing dependence on distant centralized facilities.
Micro data centers also provide organizations with a flexible approach to IT deployment. Their compact footprint, modular construction, integrated power and cooling systems, and relatively rapid installation make them suitable for manufacturing plants, retail stores, telecom sites, healthcare facilities, smart infrastructure, offices, and remote locations. Demand is further supported by the growing volume of connected devices and enterprise workloads requiring reliable computing resources outside conventional data center environments.
? Looking for Specific Data? Get a Free Customized Sample
Market Overview
A micro data center is a compact and self-contained computing environment designed to provide processing, storage, networking, cooling, security, and power-management capabilities within a relatively small physical footprint. These systems can range from enclosed racks and cabinets to modular infrastructure designed for branch offices, edge locations, factories, telecom facilities, and distributed enterprise sites.
The market is benefiting from a broader shift toward decentralized IT architecture. Organizations increasingly need computing capacity closer to data sources as connected equipment, sensors, applications, autonomous systems, and digital services generate growing volumes of information. Transferring every workload to large centralized facilities can create latency, bandwidth, cost, and resilience concerns, encouraging organizations to deploy smaller computing environments at strategic locations.
Micro data centers are particularly attractive where enterprises require rapid infrastructure expansion but do not have the space, capital requirements, or operational need for a traditional facility. Standardized designs can also simplify deployment while allowing companies to scale IT infrastructure in line with changing workload requirements.
Key Findings
-
Market value is projected at USD 6.4 billion in 2024
-
Revenue is expected to reach USD 33.0 billion by 2033
-
The market is forecast to expand at a 20.0% CAGR
-
North America is expected to hold 41.0% share in 2024
-
Edge computing remains a major demand catalyst
-
5G deployment supports distributed computing infrastructure
-
IoT growth increases demand for localized data processing
-
Modular infrastructure supports faster installation
-
Enterprises increasingly prioritize lower processing latency
-
Remote locations create new micro data center opportunities
Market Dynamics
The micro data center industry is being shaped by the convergence of cloud infrastructure, distributed computing, connected devices, automation, and enterprise digital transformation. Businesses are producing significantly larger volumes of data across geographically dispersed operations, making centralized processing alone less practical for certain real-time and latency-sensitive applications.
Micro data centers provide an intermediary infrastructure layer between endpoint devices and large cloud or hyperscale environments. This allows organizations to process critical information locally while sending selected data to larger facilities for storage, deeper analytics, backup, or long-term processing.
At the same time, enterprises are focusing more closely on business continuity. Distributed infrastructure can reduce dependence on a single centralized location and enable critical applications to continue operating even during network disruptions. These characteristics are making micro data centers increasingly relevant to mission-critical environments.
Market Trends
One of the strongest trends is the expansion of edge computing architecture. Applications involving automated manufacturing, smart cities, autonomous systems, video analytics, connected healthcare devices, and real-time customer experiences increasingly require computing resources close to the point of interaction.
Another significant trend is the integration of micro data centers with artificial intelligence workloads. Edge AI applications require local processing for immediate analytics and decision-making, particularly where transmitting large data volumes to distant facilities would create unacceptable delays.
The market is also moving toward highly modular and standardized infrastructure. Vendors are developing preconfigured units combining servers, networking, power distribution, cooling, monitoring, and physical security into integrated systems.
Major trends include:
-
Edge AI is expanding localized computing requirements
-
Modular systems are simplifying infrastructure deployment
-
Smart factories are adopting on-site processing capacity
-
5G networks are creating distributed compute opportunities
-
Remote monitoring is improving micro data center management
-
Energy efficiency is becoming a major purchase criterion
-
Integrated cooling is gaining greater importance
-
Ruggedized systems are supporting harsh environments
Growth Drivers
Expansion of Edge Computing
Edge computing is one of the most important drivers of the Global Micro Data Center Market. Organizations increasingly require data processing near users and connected devices to improve application response times and reduce dependency on distant cloud infrastructure.
This is particularly important for industrial automation, telecom networks, retail analytics, connected vehicles, digital healthcare, and smart infrastructure, where milliseconds can influence application performance.
Rapid Growth of IoT Devices
The increasing use of sensors, industrial equipment, cameras, smart meters, connected machines, and other IoT devices is generating massive amounts of distributed data. Processing this information locally can reduce bandwidth requirements and improve response times.
Micro data centers support this requirement by providing computing capacity close to IoT environments while maintaining connections with cloud platforms and enterprise data centers.
5G Network Development
5G networks support applications requiring faster communications and lower latency. As telecom providers and enterprises expand 5G-enabled services, computing infrastructure must move closer to network users and connected devices.
Micro data centers can be installed near telecom facilities, enterprise locations, and network edge environments, creating significant opportunities as 5G ecosystems expand.
Growing Need for Rapid IT Deployment
Traditional data center construction can involve extensive planning, engineering, and capital investment. Micro data centers provide a faster alternative because many solutions are standardized, prefabricated, and designed for rapid installation.
Organizations can therefore deploy additional computing resources without constructing full-scale facilities, supporting faster business expansion and digital transformation.
Market Challenges
Despite strong growth opportunities, the market faces several operational and technical challenges. Distributed infrastructure can increase management complexity because enterprises may need to supervise numerous data center locations rather than a limited number of centralized facilities.
Physical security is another important consideration. Micro data centers may be deployed in offices, warehouses, factories, telecom sites, or remote locations where infrastructure is exposed to environmental conditions or unauthorized access.
Major challenges include:
-
Distributed sites may increase maintenance complexity
-
Cybersecurity risks rise across connected edge environments
-
Physical protection is essential at remote installations
-
Cooling can be difficult in space-constrained locations
-
Initial deployment costs may affect smaller enterprises
-
Standardization remains important across distributed sites
-
Skilled personnel may be limited at remote locations
Organizations are addressing these concerns through centralized monitoring platforms, automated infrastructure management, predictive maintenance, remote access tools, and stronger cybersecurity controls.
Market Segmentation Overview
The micro data center market can be segmented based on component, organization size, application, and end-use industry. Each category reflects different infrastructure requirements and operating priorities.
By Component
The market broadly includes solutions and services. Solutions typically integrate IT racks, power systems, cooling equipment, networking infrastructure, monitoring tools, and security features. Services include installation, maintenance, consulting, integration, and infrastructure management.
By Organization Size
Large enterprises are major adopters because they typically operate multiple facilities and require distributed computing infrastructure across manufacturing plants, offices, branches, logistics sites, and customer-facing locations.
Small and medium-sized enterprises are also adopting compact data centers where conventional facilities may be impractical or unnecessarily expensive.
By Application
Important applications include edge computing, branch-office IT, remote-site infrastructure, network optimization, industrial processing, content delivery, and business continuity.
By End-Use Industry
Micro data centers are being adopted across:
-
Telecom and IT
-
Banking and financial services
-
Manufacturing
-
Healthcare
-
Retail
-
Government
-
Energy and utilities
-
Transportation and logistics
Manufacturing and telecommunications are particularly important because both sectors increasingly depend on real-time processing and distributed digital infrastructure
Regional Analysis
North America is projected to dominate the global micro data center market with a 41.0% share by the end of 2024. The region benefits from an advanced technological ecosystem, widespread adoption of edge computing, extensive cloud infrastructure, high levels of enterprise digitalization, and a strong presence of data center technology providers.
Rapid adoption of artificial intelligence, IoT, 5G, smart manufacturing, advanced retail technologies, and connected infrastructure is creating substantial demand for localized processing capacity across the United States and Canada.
Europe is also expected to represent an important market as enterprises invest in edge infrastructure, automation, smart manufacturing, telecommunications modernization, and distributed IT systems. Demand is supported by industrial digitalization and increasing requirements for reliable computing closer to operational locations.
Asia-Pacific is expected to create significant long-term opportunities due to expanding digital economies, increasing cloud adoption, rapid 5G development, industrial automation, smart-city investment, and the growing number of connected devices. Countries across the region are expanding data infrastructure to support rising internet traffic and enterprise digital services.
Competitive Landscape
The competitive landscape is characterized by established data center infrastructure companies, IT equipment manufacturers, networking providers, power-management specialists, cooling technology companies, and emerging edge-computing solution providers.
Competition is increasingly centered around compact design, deployment speed, energy efficiency, remote management, security, scalability, cooling performance, and integration with cloud and edge platforms. Providers are also developing modular solutions that can be customized for enterprise offices, industrial environments, telecom infrastructure, and remote facilities.
Strategic partnerships are becoming important as companies combine IT hardware, networking systems, cooling equipment, software platforms, and infrastructure management capabilities into unified solutions.
Key competitive priorities include:
-
Faster deployment
-
Lower energy consumption
-
Compact system design
-
Advanced remote monitoring
-
Greater physical security
-
Scalable modular architecture
-
Edge and cloud integration
-
Higher infrastructure resilience
Future Market Outlook
The future of the Micro Data Center Market is closely linked with the broader shift toward distributed computing. Enterprises are expected to continue combining centralized cloud infrastructure with localized processing environments as applications become more data-intensive and latency-sensitive.
The market is projected to expand from USD 6.4 billion in 2024 to USD 33.0 billion by 2033, reflecting the growing strategic importance of edge infrastructure. A 20.0% CAGR indicates substantial investment potential across telecom, manufacturing, healthcare, retail, financial services, government, and other sectors.
Artificial intelligence is likely to strengthen this opportunity further. As more AI inference moves closer to devices and users, organizations will require infrastructure capable of supporting accelerated computing outside traditional facilities.
Future growth areas include:
-
Edge AI infrastructure
-
Private 5G environments
-
Smart factories
-
Autonomous systems
-
Connected healthcare
-
Smart retail
-
Digital transportation
-
Industrial IoT
FAQs
1. What is the Global Micro Data Center Market Size?
The Global Micro Data Center Market Size is expected to reach USD 6.4 billion in 2024 and approximately USD 33.0 billion by 2033, expanding at a CAGR of 20.0% during the forecast period.
2. What is driving growth in the Micro Data Center Market?
Major growth drivers include increasing edge computing adoption, 5G network expansion, IoT deployment, industrial automation, artificial intelligence, cloud integration, and growing demand for low-latency data processing.
3. Which region dominates the Micro Data Center Market?
North America is projected to dominate the market with approximately 41.0% of global revenue in 2024, supported by advanced digital infrastructure and significant edge computing adoption.
4. Why are businesses adopting micro data centers?
Businesses use micro data centers to process information closer to users and devices, reduce latency, improve resilience, support remote operations, and deploy IT capacity more rapidly than traditional facilities.
5. Which industries offer major opportunities for micro data centers?
Telecommunications, manufacturing, healthcare, banking, retail, government, utilities, logistics, and transportation represent important adoption areas because these industries increasingly require distributed computing and real-time processing.
Summary of Key Insights
The Global Micro Data Center Market is entering a period of strong expansion as organizations move computing resources closer to users, machines, sensors, and applications. The market is expected to grow from USD 6.4 billion in 2024 to USD 33.0 billion by 2033, registering a 20.0% CAGR.
North America is projected to account for 41.0% of the market in 2024, supported by strong technological infrastructure, edge computing adoption, and extensive digital transformation activity.
Growth will increasingly be driven by edge computing, AI, IoT, 5G connectivity, industrial automation, modular infrastructure, and demand for low-latency processing. While cybersecurity, distributed management, cooling, and physical security remain challenges, advances in remote monitoring, automation, and integrated infrastructure are strengthening the business case for micro data centers.
As enterprise workloads become more distributed, the Micro Data Center Market is expected to become an increasingly important part of global digital infrastructure, connecting cloud platforms with localized computing environments and enabling faster, more resilient, and more efficient data processing.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0