Preserving the Value of Your Residence
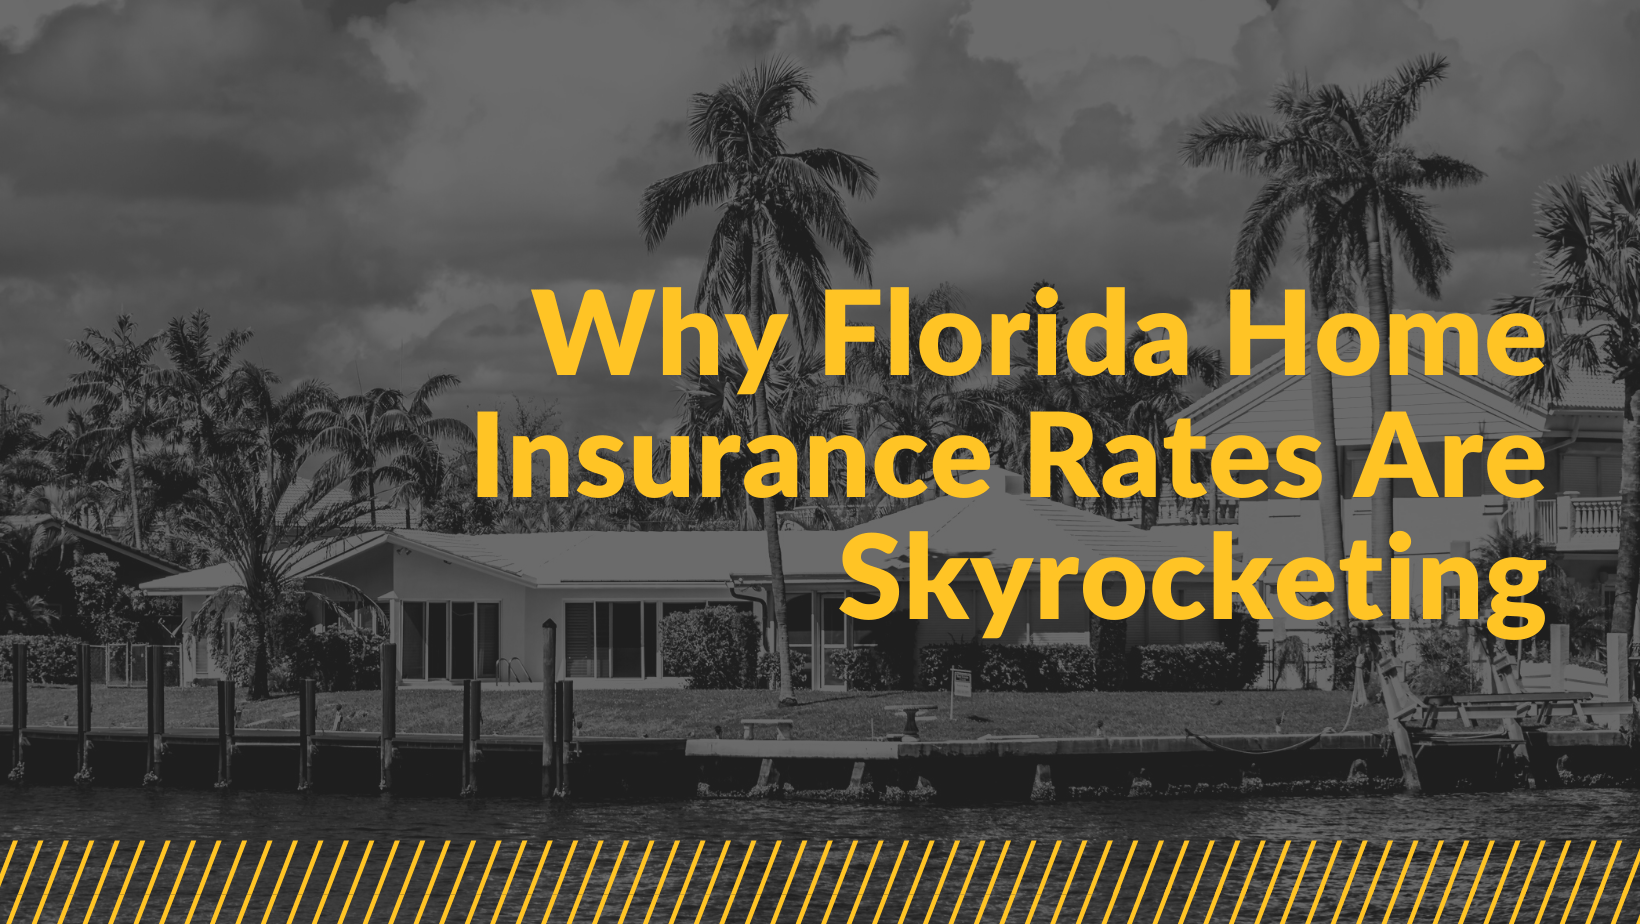
A residential property can represent a major financial commitment, so preparing for unexpected damage deserves careful attention. Repair work, temporary accommodation, and replacing damaged possessions may place considerable pressure on household budgets. Before selecting florida home insurance, residents can assess their building’s characteristics, financial obligations, and possible exposure to costly incidents. Walker Insurance Agency helps property owners explore available policies and understand the considerations involved in choosing suitable protection.
Assessing the Building’s Current Condition
The physical condition of a residence can influence the discussions involved in obtaining coverage. Roofing materials, plumbing installations, electrical components, exterior finishes, and the building’s age may all deserve consideration. Homeowners should provide reliable information about these features when requesting policy proposals. Keeping maintenance records can also help document improvements and provide useful details when reviewing the property’s circumstances.
Understanding the Cost of Reconstruction
Rebuilding a damaged house involves more than replacing visible materials. Contractors, specialized labor, debris removal, building permits, and updated construction standards may contribute to the overall expense. Property owners should examine their dwelling limits and understand how the policy determines eligible payments. Walker Insurance Agency can help explain important coverage details so homeowners can ask informed questions about potential rebuilding costs.
Taking Stock of Indoor Possessions
Many households accumulate valuable items over several years, often without realizing their combined replacement expense. Appliances, furniture, computers, kitchen equipment, clothing, and decorative belongings may all contribute to household value. Reviewing personal property provisions can help residents understand applicable limits and restrictions. An updated list accompanied by photographs and receipts can provide useful documentation if possessions are affected by a qualifying incident.
Preparing for Severe Weather
Florida’s climate makes storm preparation an important consideration for property owners. Powerful winds, hurricanes, and heavy precipitation may cause damage to different parts of a building. However, individual contracts can include special deductibles, limitations, and exclusions affecting weather-related claims. Homeowners should examine these provisions carefully and determine whether additional arrangements may be appropriate for their particular circumstances.
Investigating Separate Flood Coverage
Flooding can affect residences through rising water and other water-related conditions that may not qualify under ordinary homeowners protection. Standard home policies generally exclude flood damage, making separate flood insurance an important consideration for exposed properties. Residents can investigate their surroundings, review potential water hazards, and learn about available protection before severe weather arrives. Understanding the distinction between flooding and other covered water incidents can prevent mistaken assumptions.
Exploring Protection Against Liability Claims
Unexpected incidents involving visitors can create financial responsibilities for a property owner. Personal liability provisions may help address certain covered claims involving injuries or accidental damage to another person’s property. The actual protection depends on policy wording, applicable limits, and exclusions. Homeowners should examine these conditions carefully and consider whether their selected limits reflect their financial circumstances.
Balancing Premiums With Out-of-Pocket Costs
Choosing a policy requires consideration of both recurring payments and potential expenses after a loss. Deductibles determine how much the homeowner may need to contribute toward certain covered claims. A policy with a lower premium may include a deductible that requires a larger personal contribution following damage. Comparing these factors together can help residents select an arrangement that better matches their available savings and financial preferences.
Keeping Renovation Information Updated
Home improvement projects can change the characteristics and rebuilding requirements of a property. Replacing a roof, installing new windows, modernizing electrical systems, or expanding living space may affect the information associated with existing coverage. Homeowners should retain relevant invoices and communicate significant changes to their insurance provider. Reviewing policy details after substantial work can help determine whether adjustments deserve consideration.
Maintaining a Household Property Inventory
An organized inventory can make it easier to remember possessions and document their approximate value. Homeowners may record major purchases, photograph rooms, save receipts, and keep copies of warranties where available. Storing digital records separately from the residence can provide an additional layer of convenience. These preparations can support documentation following a covered event, although payment remains subject to the contract’s requirements.
Comparing Contractual Details
Insurance proposals should be assessed according to their actual provisions rather than their prices alone. Important differences may involve rebuilding limits, belongings protection, liability amounts, deductible arrangements, exclusions, and optional features. Reading these details can help residents understand what each proposal offers. Walker Insurance Agency can assist homeowners in examining available alternatives and identifying terms that may require further explanation.
Accounting for Property Use Changes
A residence may serve different purposes as circumstances evolve. Homeowners might begin renting out a room, operate a business from the property, or leave the building unoccupied for an extended period. Such changes may affect eligibility or the coverage available under certain contracts. Residents should communicate relevant developments promptly and ask whether their existing arrangements remain appropriate.
Making Annual Reviews a Habit
Property protection deserves regular attention as building conditions, household belongings, and construction expenses change. Reviewing policy documents each year gives homeowners an opportunity to verify important details and discuss emerging concerns. Walker Insurance Agency can help residents understand available options during these conversations. Consistent reviews encourage informed decisions and reduce reliance on outdated assumptions about a property’s protection.
Conclusion
Responsible property ownership includes preparing for repair expenses, understanding contractual restrictions, and keeping important information accurate. Residents can improve their planning by examining reconstruction estimates, documenting belongings, considering separate flood protection, and reviewing deductibles carefully. When exploring florida home insurance, Walker Insurance Agency can help homeowners understand available alternatives and identify considerations relevant to their properties. Periodic assessments can support better-informed decisions as household circumstances and residential requirements evolve.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0